Mississippi Marketplace enrollment for 2027 begins Sunday, Nov. 1, while Medicare’s separate annual enrollment period is already underway.
The dates apply to different types of coverage. The Mississippi Insurance Department urges consumers to use official channels and check plan details carefully. It does not recommend one plan for every household.
Mississippi Marketplace enrollment dates
| Coverage path | Enrollment window | Coverage timing | Official starting point |
|---|---|---|---|
| Health Insurance Marketplace | Nov. 1, 2026-Jan. 15, 2027 | Enroll by Dec. 15 for coverage beginning Jan. 1; later enrollment can begin Feb. 1 | HealthCare.gov |
| Medicare annual enrollment | Oct. 15-Dec. 7, 2026 | Approved changes take effect Jan. 1 | Medicare.gov |
| Employer-sponsored coverage | Set by each employer | Varies by plan | Employer human resources or benefits administrator |
| Medicaid and CHIP | Applications accepted year-round | Depends on eligibility and processing | Official state/federal program path |
HealthCare.gov’s dates page says Dec. 15 is the last day to enroll or change a Marketplace plan for coverage to begin Jan. 1. People who complete a selection from Dec. 16 through Jan. 15 can have coverage start Feb. 1 after paying the first premium.
Medicare follows a different calendar. The official Medicare enrollment page says its annual period runs through Dec. 7. People with Medicare cannot enroll in a Marketplace health or dental plan, according to HealthCare.gov.
Compare the same facts for every plan
A plan’s monthly price does not show its full cost. Mississippi’s regulator advises people to compare deductibles, copayments, other out-of-pocket expenses and provider networks. A low monthly premium can still produce higher costs when a household regularly uses services subject to a large deductible or out-of-network rate.
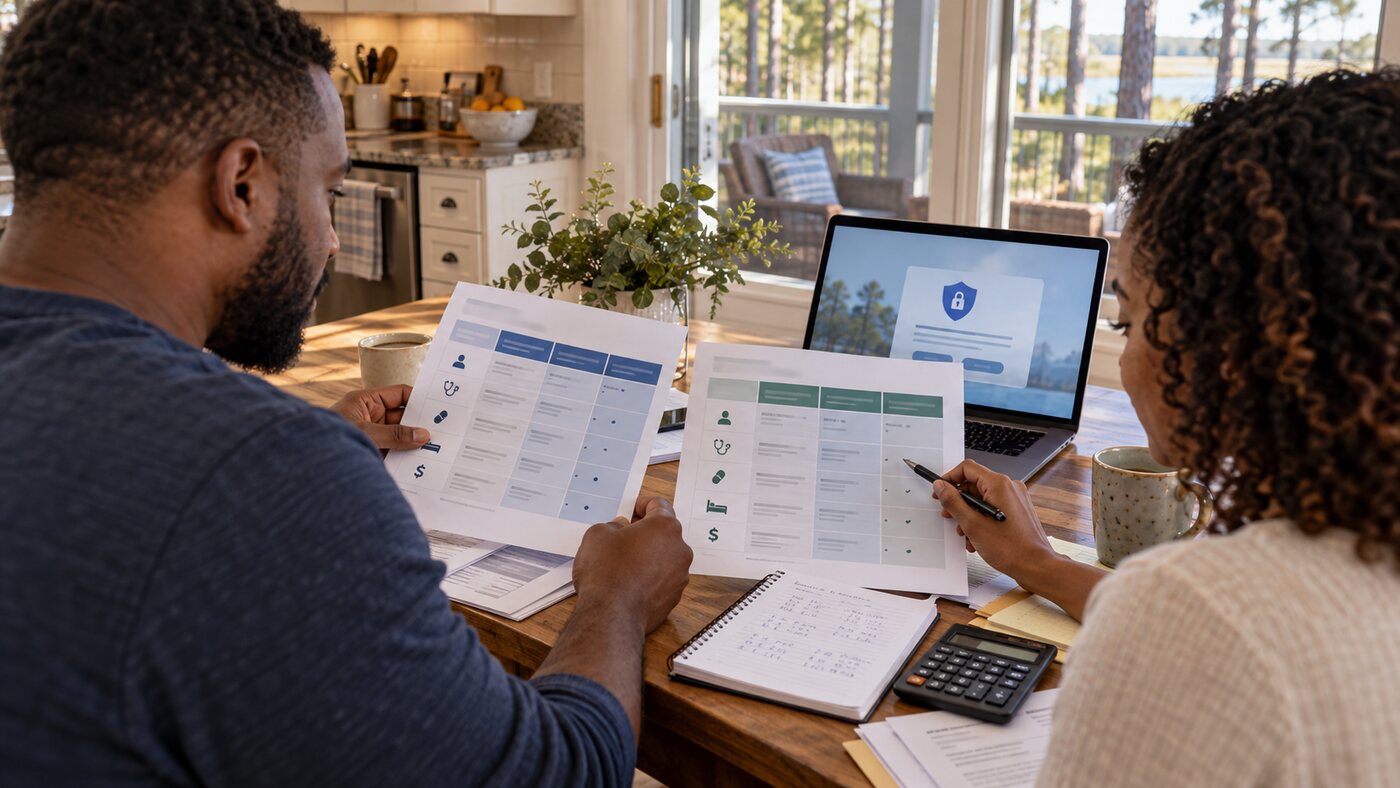
Use the same worksheet for each option:
| – Confirm that current doctors, hospitals, laboratories and pharmacies are in network. |
|---|
| – Record the deductible, out-of-pocket maximum, copayments and coinsurance. |
| – Check dependent coverage and any prior-authorization requirement. |
| – Verify the effective date and first-premium instructions before ending existing coverage. |
One comparison can be made without predicting future medical needs. Add the annual premium to the routine costs a household can reasonably estimate, then record the deductible and out-of-pocket maximum separately. The resulting rows do not identify a universally superior plan, but they prevent the monthly premium from becoming the only number considered.
Network and drug-list checks are specific rather than general. A household should search for the exact clinicians, hospitals and prescriptions it currently uses and save the plan documents supporting each result. If an insurer’s directory conflicts with information from a provider, contact the plan before enrollment and keep a record of the response.
No article can determine which coverage is appropriate for a particular person’s medical or financial circumstances. Questions about a plan should go to the insurer, employer benefits office, Medicare or the official Marketplace.
Use official enrollment channels
The safest Marketplace starting point is HealthCare.gov. A caller or advertisement that creates urgency, asks for payment by gift card or refuses to provide written plan documents should not replace the official application path.
Consumers can also use the Mississippi Insurance Department’s health insurance open enrollment guidance to review network, prescription and cost questions before selecting an option.
The Daily Quill’s Health and Wellness desk separates official enrollment dates from individualized medical advice. Applicants should avoid sending Social Security numbers, income records or payment details through an unsolicited message or unofficial form.
Documents to gather before applying
An official Marketplace application may ask for household and expected-income information used to determine eligibility and estimated savings. Gather current coverage information and the identities of household members before starting, then verify every entry on the official site before submission.
Returning customers should also treat Mississippi Marketplace enrollment as a renewal review. A returning enrollee should not assume the current premium, network or drug coverage will remain unchanged for 2027. Compare the new plan documents even if the plan name looks familiar.
For Mississippi health insurance open enrollment 2027, the first deadline with a direct coverage consequence is Dec. 15. Residents seeking Jan. 1 Marketplace coverage should compare available 2027 plans and complete the official application before that date. The broader Mississippi Marketplace enrollment window remains open through Jan. 15 for coverage that can begin Feb. 1.