A new federal charitable donation deduction may benefit Alabama taxpayers who give to qualified organizations but do not itemize deductions. Beginning with 2026 federal income-tax returns filed in 2027, eligible taxpayers may deduct up to $1,000 in qualifying cash contributions. The limit is $2,000 for married couples filing jointly.
The change matters because most people who take the standard deduction previously received no separate federal deduction for routine charitable gifts. It does not turn a donation into a dollar-for-dollar tax credit, and the maximum deduction does not mean every donor will save that amount in taxes.
The Internal Revenue Service published a new tip sheet in October explaining which gifts may qualify and what records taxpayers should keep.
How the charitable donation deduction works
The deduction applies to qualifying cash contributions made during the 2026 tax year to eligible charitable organizations. Cash can include a payment made by check or another monetary method that produces an acceptable record.
For taxpayers who do not itemize:
- The maximum is $1,000 for most filing statuses.
- The maximum is $2,000 for married taxpayers filing a joint return.
- The gift must go to an eligible organization.
- The contribution must be made during the tax year being claimed.
- The taxpayer must keep required records.
The IRS overview of the new deduction says noncash property, including clothing or stock, does not qualify for this particular non-itemizer provision. Contributions to donor-advised funds and certain supporting organizations are also excluded.
Gifts made directly to an individual are not deductible as charitable contributions, even when the recipient has a genuine need.
Records Alabama donors should keep
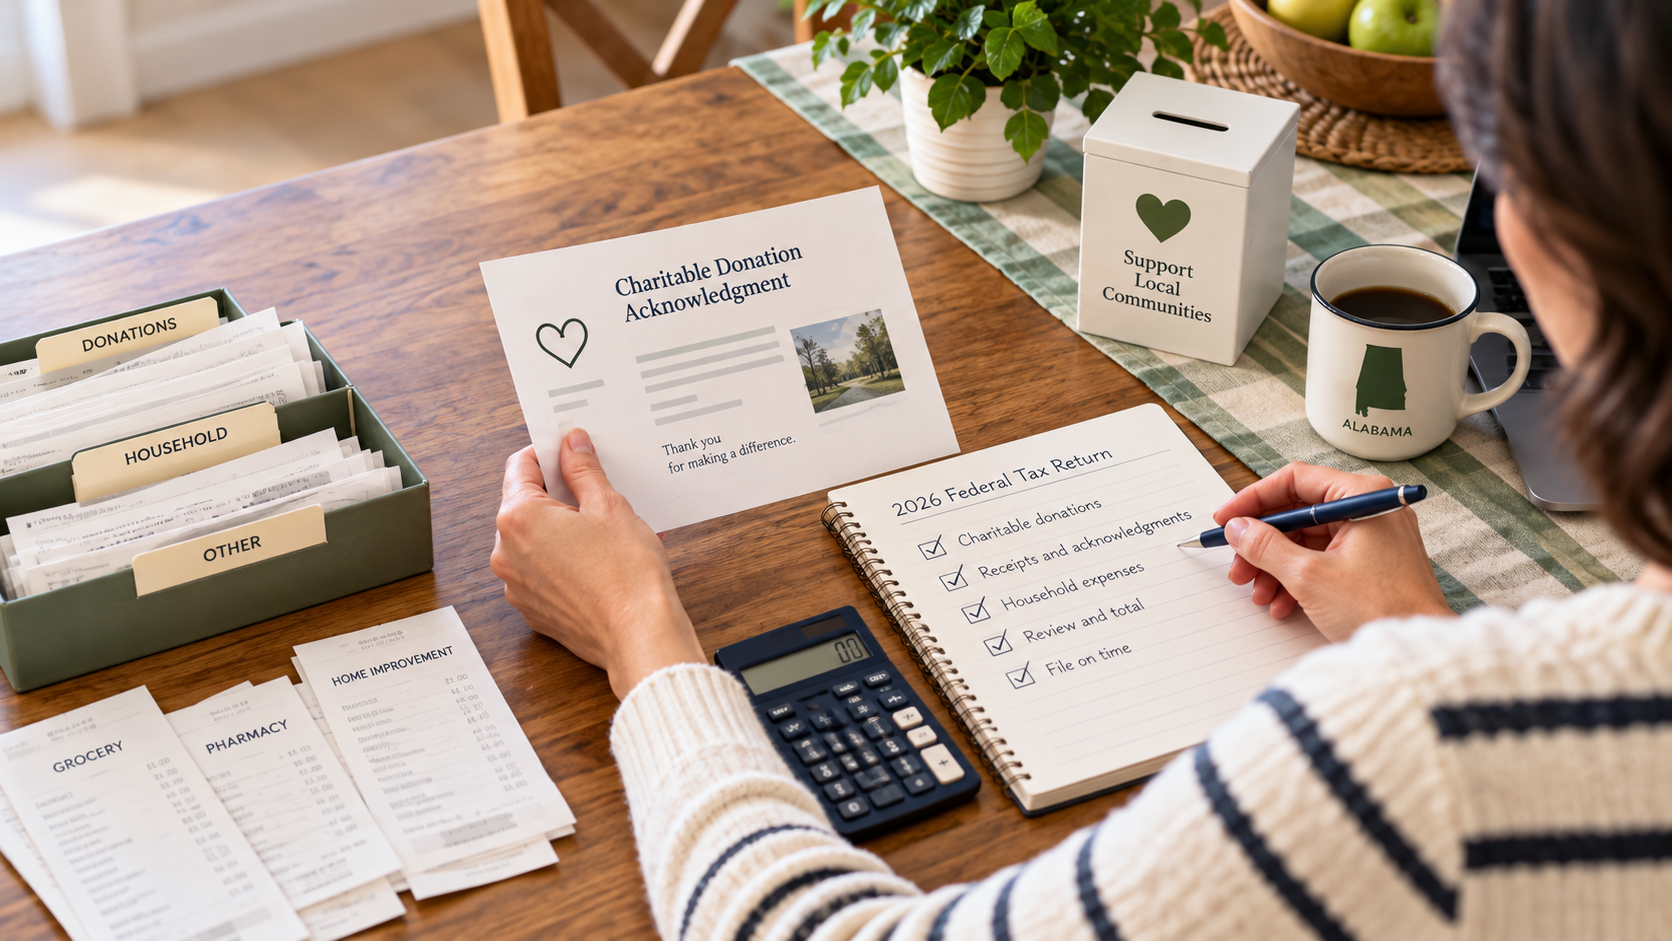
The IRS advises taxpayers to save receipts, canceled checks or bank records showing the organization, date and amount. A cash contribution cannot be deducted without a reliable written record.
To claim the charitable donation deduction, taxpayers should be able to connect each amount claimed to an acceptable written record.
For a contribution of $250 or more, the donor generally needs a contemporaneous written acknowledgment from the organization. That acknowledgment should describe whether the donor received goods or services in return. When a fundraiser provides a meal, ticket or other benefit, only the part of the payment above the fair market value of that benefit may qualify.
The IRS’s Publication 6196 provides a short checklist for non-itemizers. Taxpayers can also use the agency’s Tax Exempt Organization Search, linked from Tax Topic 506, to confirm that an organization is eligible to receive deductible contributions.
File each receipt with the other 2026 tax documents when the donation is made; a complete folder is easier to verify than a year-end memory exercise. A receipt should not include unnecessary sensitive information, and donors should be cautious about unsolicited messages that pressure them to give immediately.
What this change does not cover
The new rule does not make every donation deductible. It also does not replace the more detailed rules that apply to taxpayers who itemize, donate property, give vehicles or make unusually large or complex gifts.
The charitable donation deduction does not apply to every gift, and it should not be used for donations that fall outside the federal requirements.
Congress enacted the provision in Section 70424 of Public Law 119-21. The law sets the federal maximum, while IRS guidance explains the records and organization requirements taxpayers must follow.
Alabama taxpayers should use the final 2026 Form 1040 instructions when they become available. Anyone unsure about eligibility or documentation should consult current IRS guidance or a qualified tax professional who can review the specific facts.
The charitable donation deduction should be checked against the final filing instructions before a 2026 return is submitted.
A year-end review for donors
Before Dec. 31, donors considering the charitable donation deduction can compare receipts with bank records, verify each organization’s eligibility and request any missing acknowledgment. Keep the documents with the 2026 return rather than sending them to the IRS unless requested. If a receipt describes goods or services received in exchange, note the deductible portion separately.
Taxpayers should calculate the charitable donation deduction from their own qualifying records. Those following other national policy changes can visit The Daily Quill’s United States news section. The safest filing decision should still be based on the final IRS instructions and the taxpayer’s own records.
This article provides general public information and is not individualized tax or legal advice.